Did the Fed Raise or Cut Interest Rates in September 2026?
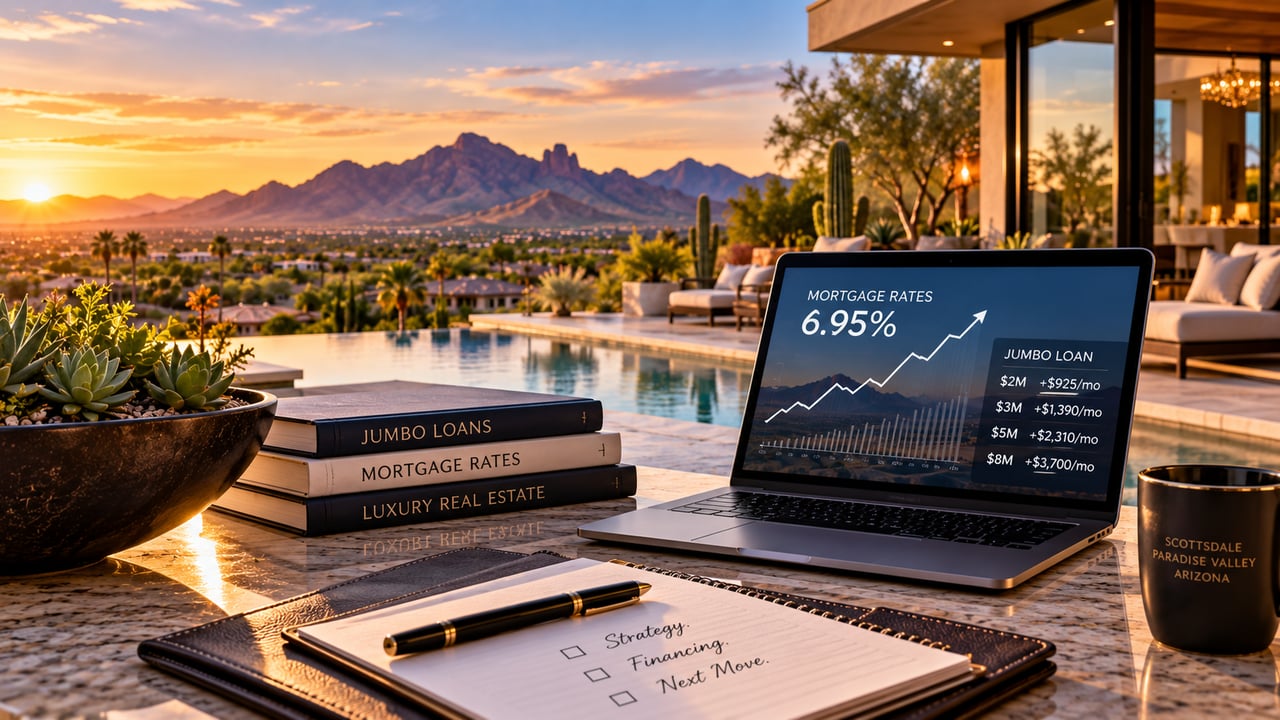
The Federal Reserve raised its benchmark rate on September 16, 2026, moving the federal funds target to 3.75%–4% in response to persistent inflation — the opposite move many buyers and lenders had been expecting after months of cut speculation. Mortgage rates followed, with 30-year rates climbing to roughly 6.95%. For a financed luxury purchase in the $2M–$8M range, that shift adds real money to the monthly payment, not just a rounding error.
By Teresa Hague | October 2, 2026
If you paused your search over the summer expecting rates to ease by fall, the news from mid-September caught a lot of people off guard. The Fed didn't cut. It hiked, and mortgage rates moved with it. If you're financing any part of a luxury purchase in Scottsdale or Paradise Valley, it's worth understanding exactly what that means in dollars before you go back out and look.
The Math That Actually Matters
Rate headlines are abstract. A monthly payment isn't. Here's the difference between a rate in the mid-6% range, which is roughly where jumbo pricing sat earlier this year, and today's post-hike environment near 6.95%, on a 30-year fixed jumbo loan at a few price points common in this market:
- $2,000,000 loan: roughly $925 more per month, or about $11,100 more per year
- $3,000,000 loan: roughly $1,390 more per month, or about $16,600 more per year
- $5,000,000 loan: roughly $2,310 more per month, or about $27,700 more per year
- $8,000,000 loan: roughly $3,700 more per month, or about $44,400 more per year
These are illustrative, not a quote — your actual rate depends on your lender, your loan structure, points, and your overall financial picture. But the pattern holds at every price point: on a jumbo loan, a fraction of a percentage point in rate translates into tens of thousands of dollars a year, not a few extra dollars a month.
This is precisely the kind of recalculation worth doing before you write an offer, not after.
Why This Hike Caught People Off Guard
Coming into September, a lot of forecasting pointed toward the Fed easing policy as inflation cooled earlier in the year. Instead, inflation data firmed back up, and the Fed moved the other direction — its benchmark rate landing at 3.75%–4%. Lenders repriced almost immediately, and 30-year mortgage rates pushed up to around 6.95%, among the highest levels buyers have seen in this cycle.
For buyers using conventional financing on a conforming loan, rate moves like this are painful but familiar territory. For jumbo borrowers — which describes most financed purchases in Scottsdale and Paradise Valley's $1.5M+ segment — the exposure is larger in absolute dollar terms simply because the loan amounts are larger. A move that costs a typical buyer $150 a month can cost a jumbo borrower $2,000 or more.
What This Means If You're Financing a Purchase Right Now
A few things worth doing before you keep shopping:
- Re-run your numbers with your lender, not with a generic online calculator. Jumbo pricing, points, and rate locks vary meaningfully by lender and loan size, and a true picture needs your actual loan officer.
- Ask about rate buydowns and points. On a large loan amount, paying points to buy down the rate can make more sense than it would on a smaller conforming loan, because the monthly savings compound faster.
- Revisit whether a larger down payment changes your tier. Depending on your lender, crossing certain loan-size thresholds can affect pricing; a slightly larger down payment sometimes buys a meaningfully better rate.
- Factor the new payment into your offer strategy, not just your pre-approval. A property that worked financially at 6.25% may need a different offer price — or a different negotiating approach — at 6.95%.
We covered the broader relationship between mortgage rates and this market in more detail in how today's mortgage rates impact luxury buyers in Scottsdale and Paradise Valley, and this September move is exactly the kind of shift that post anticipated. The rate environment can change again before you close — which is exactly why it's worth having a strategy conversation now rather than assuming your spring numbers still hold.
Frequently Asked Questions
Did mortgage rates go up or down in September 2026?
They went up. The Federal Reserve raised its benchmark rate to 3.75%–4% on September 16, 2026, and 30-year mortgage rates followed, rising to roughly 6.95%.
How much more does a 6.95% rate cost versus 6.25% on a jumbo loan?
On a $5 million loan, the difference is roughly $2,300 more per month, or about $27,700 more per year. The gap scales up or down with the loan amount — larger loans see a larger dollar impact from the same rate change.
Should I wait for rates to come back down before buying in Scottsdale?
That depends on your timeline and the specific property, not just the rate environment. Rates are unpredictable in either direction, and waiting also means competing with whoever else is waiting for the same signal — which can offset any rate savings if demand picks back up.
Does a Fed rate hike affect jumbo loans the same way it affects conventional loans?
The direction is the same, but the dollar impact is larger on a jumbo loan simply because the loan amount is larger. A rate move that adds $150 a month to a typical mortgage can add $2,000 or more to a multimillion-dollar jumbo loan.
What can I do right now if a higher rate changes what I can afford?
Talk to your lender about points, rate buydowns, and how a larger down payment might affect your pricing tier, and revisit your offer strategy on any property you're considering with the new numbers in hand rather than your pre-approval from earlier this year.
Rate swings like this one are exactly why a financing plan built in the spring can't be assumed to still hold by fall. If you're actively looking at a purchase in Scottsdale or Paradise Valley and want help thinking through what this rate environment means for your specific budget and timeline, reach out to Hague Luxury Network — we work through financing strategy with every buyer client before they're out making offers, not after.
About Teresa Hague
Teresa Hague leads Hague Luxury Network, Arizona's leading luxury real estate team, specializing in high-end homes and estates in Paradise Valley, Scottsdale, Arcadia, and neighboring premier communities. The team combines local market intelligence, powerful digital marketing, and the 72SOLD Luxury platform to help luxury home sellers achieve maximum exposure and exceptional results — with a curated, full-service experience from pricing strategy and preparation to photography, film, and negotiation.